Planning Financial Protection Around a Military Career
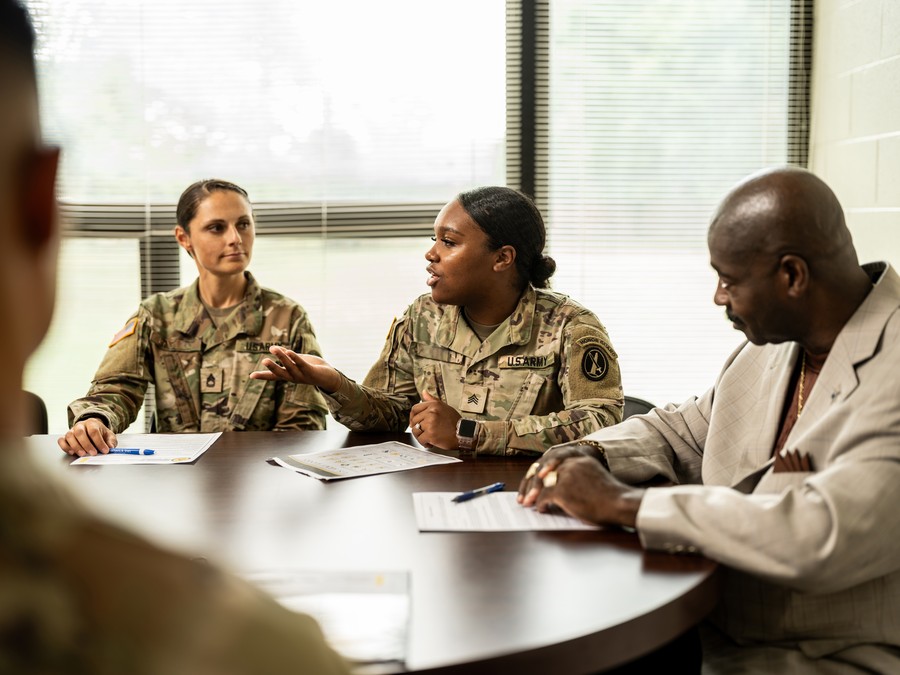
Serving in the Armed Forces can mean approaching everyday life differently. Deployments, overseas postings, specialist duties and frequent changes in circumstances can all be part of a military career.
These differences can also influence financial planning. While mortgages, family responsibilities and long-term goals may be similar to those of civilians, the nature of military work can introduce additional considerations when arranging financial protection.
Understanding these factors can help serving personnel make informed decisions about protecting the people who depend on them.
Why Occupation Can Matter
Occupation can be relevant when applying for financial protection because different jobs involve different levels and types of risk.
Military service covers an extremely broad range of roles. Someone working primarily in an office environment may have very different duties from personnel involved in aviation, diving, bomb disposal or other specialist activities.
This means describing an occupation simply as “military” may not provide the complete picture. The specific role and duties involved can be important when an application is assessed.
Consider Your Current Responsibilities
Before looking at policies, it is useful to understand what you actually want financial protection to achieve.
For someone with a mortgage, keeping the family home financially manageable may be a priority. Parents may want to provide additional security for their children, while couples may depend on both incomes to cover everyday household costs.
Looking at debts, income and regular commitments can help establish what level of protection may be appropriate for the household.
Existing Benefits Are Part of the Picture
Serving personnel may already have certain benefits connected to their employment. These should be considered when looking at wider financial protection rather than ignored.
Understanding what is already available makes it easier to identify any potential gaps.
It is also worth considering whether existing arrangements would provide the level of financial support someone wants for their family. Personal circumstances vary, so the appropriate approach will depend on individual responsibilities and longer-term plans.
Deployments Can Add Another Consideration
Military careers can involve periods overseas, sometimes with relatively little notice.
For anyone considering Military life insurance, it can therefore be useful to understand how their role, duties and potential deployments may be considered when looking for protection.
Being clear about these circumstances from the beginning can help ensure the application reflects the reality of someone’s work rather than relying on a broad occupational title.
Specialist Roles Can Be Very Different
The Armed Forces contain hundreds of different occupations.
Engineers, medical personnel, logistics specialists, infantry soldiers and aircrew may all serve within the military, but their day-to-day responsibilities can look completely different.
Some personnel also take part in activities that carry additional considerations, whether through their normal duties or specialist training.
Providing accurate information about these activities can help create a clearer picture during an application.
Life Outside Work Still Matters
Occupation is only one part of someone’s circumstances.
Military personnel have the same wider considerations as anyone else when thinking about financial protection. Age, health, smoking status and the amount and type of cover requested may all be relevant depending on the application.
Hobbies can matter too. Someone who participates in climbing, motorsport, diving or other adventurous activities outside work may have additional information to provide.
The overall picture is therefore usually more useful than focusing on military service alone.
Review Protection When Circumstances Change
Military careers can involve significant changes over relatively short periods.
Personnel may move between roles, receive promotions, relocate or leave the Armed Forces altogether. Personal circumstances can change at the same time through marriage, children or buying a home.
Financial protection arranged earlier in someone’s career may therefore no longer reflect their current responsibilities.
Periodic reviews can help confirm whether existing arrangements remain suitable or whether circumstances have changed enough to warrant another look.
Specialist Support Can Make the Process Easier
Finding appropriate protection can feel more complicated when an occupation involves duties that fall outside a typical civilian working environment.
Companies such as Sports Financial Services work with people whose occupations, sports or other circumstances may require a more specialist approach to financial protection.
For military personnel, this can help provide a clearer understanding of what information may be required and how different aspects of their role could form part of an application.
Planning Beyond Active Service
A military career will eventually come to an end, whether through retirement or a move into civilian employment.
That transition can be a useful point to review wider finances. Income may change, workplace benefits can be different and family priorities may have developed considerably since someone first joined the Armed Forces.
Protection should reflect someone’s life as it exists now rather than the circumstances they had when a policy was originally arranged.
Protecting the People Who Depend on You
For most people, the main reason for considering financial protection is straightforward. They want greater confidence that the people closest to them would have financial support if something happened.
Military service can introduce some additional factors into that planning, but the underlying questions remain familiar. What financial commitments exist? Who relies on the household income? What arrangements are already in place?
Answering those questions provides a practical starting point.
Military careers can be unpredictable, but financial planning does not need to be. By understanding existing benefits, considering personal responsibilities and exploring appropriate protection, serving personnel can build arrangements around both their career and the people who matter most to them.